|
|

|
|
UAE Market Major
News/Highlights
|
|
| |
IHC,
Adani enter deals with India's Odisha state for
USD22bn projects, as per zawya.
International
Holding Company (IHC) and India’s Adani Group have
signed a memorandum of understanding (MoU) with the
Government of Odisha for 14 projects covering trade and
the development of a port, with an investment outlay of
USD22 billion. Earlier, IHC and Adani Group signed an
agreement to develop an aluminium smelter and a
manufacturing plant with an investment outlay of USD
11.5 bn. A major outcome was the signing of an MoU
between the Government of Odisha, IHC and the Adani
Group to explore 14 new projects with an indicative
investment of USD2.105 trillion and employment potential
for approximately 8,68,200 people. The proposed
portfolio spans metal downstream industries, slurry
pipelines, critical minerals and rare earths, chemicals
and petrochemical derivatives, renewable energy
equipment, healthcare, industrial infrastructure,
tourism, skill development and sports infrastructure.
The MoUs were signed during the first day of Odisha
Chief Minister Mohan Charan Majhi’s UAE visit. The
engagements brought together leading businesses and
investment institutions to expand the state’s
international investment partnerships during the visit
from September 8 to 12.
Covestro,
Fertiglobe and MB Energy Sign MoU to Explore Ammonia
Supply Chain. Covestro,
Fertiglobe and MB Energy have signed a MoU to explore
collaboration across the ammonia value chain in Germany
and Europe. The MoU was signed during the visit to
Germany of His Highness Sheikh Mohamed bin Zayed Al
Nahyan, President of the United Arab Emirates. The
collaboration brings together Fertiglobe’s global
ammonia production and supply capabilities, MB Energy’s
energy infrastructure and logistics expertise, and
Covestro’s position as a major industrial consumer of
ammonia in Germany. Under the MoU, Fertiglobe will
explore the potential supply of ammonia through an
import terminal proposed to be built and operated by MB
Energy, an independent and integrated energy company, at
Blumensand in Hamburg. As part of the collaboration,
Fertiglobe will also explore potential equity investment
in the Hamburg terminal. Covestro will evaluate the
potential offtake of ammonia delivered through the
terminal for use as feedstock in its production and/or
to meet hydrogen supply requirements. By developing an
additional route for ammonia imports into Germany, the
collaboration has the potential to diversify supply
options and strengthen the resilience of supply chains
serving European industry. Parties to evaluate
conventional, lower-carbon and renewable ammonia
opportunities to strengthen the resilience and
diversification of ammonia supply to Germany and Europe,
while supporting the region’s energy
transformation.
Space42
and Viasat sign binding agreement to co-found
Equatys, creating the first shared space and ground
infrastructure platform for global Direct-to Device
and advanced MSS connectivity. The
signing of the binding agreement provides for up to USD1
billion in combined equity commitments from Space42 and
Viasat as the initial co-founders of Equatys.
Simultaneous signing of agreement to step up funding
accelerates program development of the initial satellite
constellation; Scalable constellation’s initial tranche
to be awarded upon formation of Equatys with planned
appointment of Viasat as prime technology contractor.
Equatys intended to offer a foundation for choice and
interoperability and provide compelling economic
benefits from geographic and spectral efficiencies to
participating global, regional and national space
operators using licensed Mobile Satellite Services (MSS)
spectrum and/or Supplemental Coverage from Space (SCS)
spectrum. Tower Company model intended to deliver
compounding economic value to satellite service
providers as the user base grows by reducing each
participant’s share of satellite costs, improving
spectrum efficiencies, and improving network performance
and availability at scales otherwise beyond the reach of
each individual operator; Compound growth model provides
attractive return potential for additional strategic and
financial partners as the system scales
Tabreed
Announces Appointment of Dr Yousif Al Hammadi as
Chief Executive Officer.
Borouge
has announced that
it has bought back 1,000,000 shares at an average price
of AED2.378/per share on 11th September
2026.
Talabat
announced that
it has bought back 1,500,000 shares at an average price
of AED1.160/per share on 11th September
2026.
|
|
|
|
ADX |
DFM |
Total UAE Trading |
Foreign Net Flow |
|
10,112.6 |
5,941.2 |
AED 1,723bn |
AED 56mn |
|
0.0% |
0.6% |
ADX + DFM turnover |
Across ADX & DFM |
|
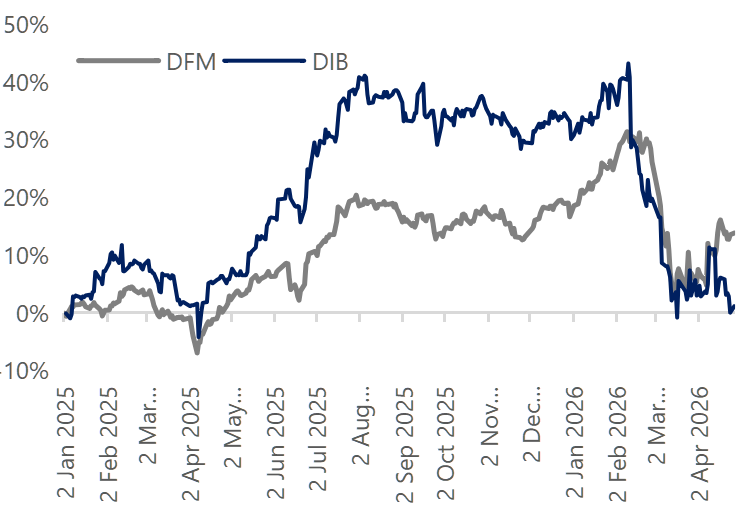
ADX & DFM 1 Year Performance |
|
(AED mn) |
Buy |
Sell |
Net |
|
ADX |
1,161 |
1,161 |
- |
|
Local |
693 |
723 |
-30 |
|
Foreign |
468 |
438 |
30 |
|
Company |
761 |
763 |
-2 |
|
Individual |
400 |
398 |
2 |
|
DFM |
562 |
562 |
0 |
|
Local |
329 |
355 |
-26 |
|
Foreign |
233 |
207 |
26 |
|
Company |
338 |
305 |
33 |
|
Individual |
224 |
257 |
-33 |
|
Total |
1,723 |
1,723 |
0 |
|
Local |
1,022 |
1,078 |
-56 |
|
Foreign |
701 |
645 |
56 |
|
Source: ADX and DFM |
|
|
|
|
|
GCC Market Major
News/Highlights
|
|
| |
Trading
value in GCC stock markets reaches USD618bn, with
market capitalisation at USD3.9tr.
GCC
stock markets recorded trading in approximately 401.7
billion shares during 2025, an increase of 19.5%
compared with the previous year, with the value of
shares traded reaching approximately USD618 billion.
This is according to the latest data released by the
Statistical Centre for the Cooperation Council for the
Arab Countries of the Gulf (GCC-Stat). The general
composite index measuring GCC stock market performance
stood at approximately 165.2 points at the end of 2025,
down 3.8% compared with the end of 2024. The total
market capitalisation of GCC stock markets reached
approximately USD3.9 trillion in 2025, a decline of 6.2%
compared with the previous year. A total of 779
companies were listed on GCC stock markets. Of these,
the shares of 756 companies were eligible for trading by
citizens of Gulf Cooperation Council (GCC) countries on
GCC markets, representing 97% of all listed companies.
The proportion reached 100% on Bahrain Bourse (BHB),
Muscat Stock Exchange (MSX), Qatar Stock Exchange (QSE)
and Boursa Kuwait.
Saudi
pipeline outage threatens loss of 4% of global oil
supply. Saudi
Arabia will run out of oil stocks for exports if it
doesn't restart its major pipeline to the Red Sea within
days, leading to a loss of up to 4% of global supply,
Saudi oil buyers and traders said. A further decline in
Saudi flows will worsen the global supply crunch, which
has already pushed global fuel prices to record highs,
spurred inflation around the world and sent U.S. bond
yields to the highest levels since the 2008 financial
crisis.
Egypt’s
Pharco Pharmaceuticals targets mid-2027 start for
Saudi plant. Egypt’s
Pharco Pharmaceuticals plans to start operations at a
new factory it is building in Saudi Arabia’s Medina by
mid-2027, Chairman Sherine Helmy said on the sidelines
of an event in Cairo on Tuesday. Company investing
$49mln in new Medina facility
|
|
|

|
|
Regional Market Performance
|
|
|
Indices |
Close |
Change |
|
1D |
1M |
YTD |
1Y |
|
ADX |
10,112.6 |
0.0% |
1% |
1% |
2% |
|
DFM |
5,941.2 |
0.6% |
1% |
-2% |
0% |
|
TASI (Saudi) |
10,865 |
-1.3% |
0% |
4% |
4% |
|
QSI (Qatar) |
9,849 |
0.2% |
-2% |
-8% |
-11% |
|
BKM (Kuwait) |
9,306 |
-0.2% |
0% |
-2% |
0% |
|
MSX (Oman) |
7,647 |
0.0% |
2% |
30% |
50% |
|
BHSEASI (Bahrain) |
1,930 |
0.0% |
-1% |
-7% |
-1% |
|
EGX (Egypt) |
55,665 |
-1.1% |
2% |
33% |
59% |
|
Source: Reuters, IS Research. |
|
|
|
|
Global Markets
News/Highlights
|
|
| |
Share
markets slid in Asia on Monday, dragged down by AI
stocks, while supply concerns in the Middle East
caused oil prices to spike anew, and investors
braced for likely interest rate hikes in both the
United States and Japan this week.
A
hot U.S. consumer price report on Friday led markets to
price in an 86% chance the Federal Reserve will lift
rates by 25 basis points on Wednesday, and move again by
December. It would be the first hike since mid-2023.
Japan's
Nikkei fell 0.8%, while South Korea dropped 2.1% after
the calls for a slowdown in AI development.
MSCI's
broadest index of Asia-Pacific shares outside Japan
slipped 0.8%, while Chinese blue chips eased
0.4%.
In
Europe, EUROSTOXX 50 futures lost 0.2%, while DAX
futures fell 0.1% and FTSE futures firmed 0.2%. On Wall
Street, S&P 500 futures lost 0.4%, while Nasdaq
futures fell 1.1%.
Yields
on 10-year Treasury notes were stuck at 4.974%, having
been sold heavily in recent weeks. Just last week alone,
2-year yields rose a steep 26 basis points, while
10-year yields added 19 basis points as the curve
flattened.
Markets
also imply around a 76% chance the Bank of Japan will
lift its cash rate by a quarter point, to 1.25%, when it
meets on Friday. The BOJ is also expected to sound
hawkish on further tightening as it struggles to prevent
a relapse in the yen after market intervention helped to
pull it from a 40-year low.
|
|
|
|
|
|
Global Indices Performance
|
|
|
Indices |
Close |
Change |
|
1D |
1M |
YTD |
1Y |
|
DJI |
52,573 |
1.0% |
-2% |
9% |
14% |
|
S&P 500 |
7,657 |
0.9% |
-1% |
12% |
16% |
|
Nasdaq |
26,333 |
1.0% |
0% |
13% |
19% |
|
FTSE |
10,650 |
0.4% |
-2% |
7% |
15% |
|
DAX |
25,569 |
0.8% |
-3% |
4% |
8% |
|
KOSPI |
6,910 |
-1.8% |
9% |
64% |
107% |
|
Nikkei225 |
64,011 |
-1.9% |
-4% |
27% |
44% |
|
HSI |
24,806 |
-0.6% |
-3% |
-3% |
-5% |
|
MSCI EM |
1,722 |
-1.3% |
3% |
23% |
31% |
|
MSCI Asia |
278 |
-1.2% |
2% |
22% |
27% |
|
US Futures |
7,660 |
0.8% |
-1% |
10% |
13% |
|
Source: Reuters, IS Research. |
|
Rates |
Current |
Change |
|
1D |
1W |
6M |
1Y |
|
US 2yr Bond |
4.61% |
-0.02% |
0.24% |
0.89% |
1.05% |
|
US 10yr Bond |
4.96% |
0.00% |
0.18% |
0.69% |
0.90% |
|
US 30yr Bond |
5.36% |
0.01% |
0.12% |
0.46% |
0.68% |
|
EUR 2yr Bond |
3.20% |
0.00% |
0.19% |
0.75% |
1.18% |
|
EUR 10yr Bond |
3.50% |
0.00% |
0.12% |
0.52% |
0.79% |
|
EUR 30yr Bond |
3.90% |
0.00% |
0.05% |
0.37% |
0.60% |
|
JPY 2yr Bond |
1.84% |
0.00% |
0.00% |
0.54% |
0.97% |
|
JPY 10yr Bond |
2.99% |
0.01% |
0.07% |
0.74% |
1.40% |
|
JPY 30yr Bond |
4.06% |
0.02% |
0.07% |
0.55% |
0.85% |
|
Source: Bloomberg, IS Research |
|
|
| |
Oil
prices rose more than 3% on Monday, after attacks on
ships in the Gulf compounded supply concerns
following the closure of a key Saudi oil
pipeline.
Brent
crude futures rose 3.1%, to USD107.82 per barrel. WTI
futures gained 3.2%, to USD103.22 per barrel.
Saudi
Arabia's East-West oil pipeline was temporarily shut
following a drone attack, according to Saudi officials.
The shutdown of the pipeline, which helps Saudi Arabia
avoid the Strait of Hormuz and re-route its exports,
threatens up to 4% of global oil supply.
With
the pipeline out of service, Yanbu has enough inventory
to cover just five to seven days of exports, according
to three industry sources familiar with Saudi Arabia's
exports.
Meanwhile,
a vessel in the Strait of Hormuz was struck by a
projectile, causing a fire and forcing the crew to be
evacuated, the British maritime security agency UKMTO
said on Sunday.
Oil
surged 8% higher last week due to the disruptions,
rising above USD100 for the first time since
July.
|
|
|
|
Commodities/ Bitcoin |
Current |
Price Change |
|
1D |
1W |
6M |
1Y |
|
Brent (USD/bbl) |
106.7 |
2.0% |
10.0% |
3.5% |
59.3% |
|
WTI (USD/bbl) |
102.2 |
2.1% |
11.7% |
3.5% |
63.0% |
|
Nat. Gas (USD/MMBtu) |
2.9 |
2.0% |
-2.9% |
-7.7% |
-1.8% |
|
Gold (USD/oz) |
4,335.1 |
-0.3% |
-1.6% |
-13.6% |
19.0% |
|
Silver |
64.0 |
-0.8% |
-3.3% |
-20.6% |
51.6% |
|
Copper (USD/lb) |
639.5 |
-1.2% |
-3.1% |
11.9% |
39.4% |
|
Urea (USD/Ton) |
507.5 |
0.0% |
2.0% |
-27.5% |
16.0% |
|
Coal (USD/Ton) |
126.6 |
0.0% |
-0.8% |
13.2% |
30.2% |
|
Ammonia (USD/Ton) |
437.5 |
0.0% |
0.0% |
-20.5% |
26.8% |
|
Polyethylene (CNY/MT) |
9,100.0 |
-0.7% |
2.1% |
26.6% |
26.5% |
|
Bitcoin (USD) |
77,532.0 |
0.3% |
-2.1% |
9.5% |
-33.1% |
|
Source: Bloomberg, IS Research |
|
|
|
|
|
|
Company |
MCAP (AEDm) |
Price (AED) |
Day (%) |
Valuation TTM P/E |
Div YLD (%)^ |
|
IHC |
844,536 |
385.00 |
0.0% |
36.56 |
- |
|
TAQA |
295,710 |
2.63 |
-0.4% |
39.63 |
1.7% |
|
ADNOCGAS |
269,405 |
3.51 |
1.2% |
14.67 |
4.9% |
|
ENBD |
204,663 |
32.40 |
7.2% |
8.64 |
3.1% |
|
FAB |
203,944 |
18.46 |
3.5% |
10.03 |
4.3% |
|
EAND |
173,940 |
20.00 |
3.3% |
14.63 |
4.5% |
|
DEWA |
141,004 |
2.82 |
1.4% |
16.11 |
4.4% |
|
ADCB |
121,851 |
15.40 |
-1.2% |
9.98 |
4.1% |
|
Emaar Prop. |
115,084 |
13.02 |
2.4% |
6.09 |
7.7% |
|
ADNOC Drill. |
98,243 |
6.14 |
0.2% |
18.37 |
3.5% |
|
Alpha Dhabi |
82,402 |
8.24 |
1.4% |
8.50 |
2.4% |
|
ADIB |
79,688 |
21.94 |
1.2% |
12.38 |
4.4% |
|
2POINTZERO |
78,116 |
2.26 |
2.3% |
7.30 |
- |
|
Borouge |
77,852 |
2.59 |
1.2% |
6.1 |
6.3% |
|
Aldar |
70,766 |
9.00 |
6.0% |
8.94 |
2.3% |
|
Emaar Dev. |
60,802 |
15.20 |
2.6% |
4.93 |
6.6% |
|
DIB |
57,783 |
7.98 |
2.6% |
8.09 |
4.4% |
|
DU |
53,036 |
11.70 |
0.5% |
17.58 |
5.5% |
|
Modon |
51,658 |
3.16 |
1.6% |
12.85 |
- |
|
ADNOC Dist. |
50,126 |
4.01 |
1.3% |
17.13 |
5.1% |
|
Salik |
45,751 |
6.10 |
2.5% |
29.48 |
3.4% |
|
ADNOCLS |
45,502 |
6.15 |
1.0% |
14.38 |
2.6% |
|
Air Arabia |
27,488 |
5.89 |
5.9% |
17.49 |
5.1% |
|
Pure Health |
25,890 |
2.33 |
4.0% |
13.73 |
2.3% |
|
AD Ports |
24,178 |
4.75 |
2.4% |
13.64 |
- |
|
Fertiglobe |
23,161 |
2.79 |
3.0% |
11.15 |
4.2% |
|
Presight |
21,033 |
3.75 |
1.4% |
35.65 |
- |
|
NMDC |
18,053 |
21.38 |
3.5% |
5.54 |
4.7% |
|
Americana |
17,353 |
2.06 |
1.0% |
18.83 |
4.3% |
|
Empower |
17,000 |
1.70 |
3.0% |
16.08 |
5.1% |
|
NMDC Energy |
15,150 |
3.03 |
-0.7% |
10.35 |
5.3% |
|
DFM |
12,400 |
1.55 |
4.0% |
12.19 |
4.2% |
|
LuLu Retail |
10,329 |
1.00 |
0.0% |
15.49 |
7.0% |
|
|
|
|
Upcoming Corporate Events
|
|
|
Date |
Company |
Event |
|
22-Jun |
BILDCO |
BoD/General |
|
24-Jun |
Ektittab |
General Meeting |
|
25-Jun |
Gulf Navigation |
BoD/General |
|
26-Jun |
Borouge |
General Meeting |
|
29-Jun |
MBME Group |
AGM |
|
29-Jun |
Sagasse Investment Company |
AGM |
|
|
|
|
This document has been prepared by International Securities
LLC ("International Securities"). It is being shared with clients and
potential investors solely for informational purposes. By accepting this document, the
recipient unconditionally agrees that it is intended for the exclusive use of the
persons to whom it is addressed and must not be copied, reproduced, distributed,
communicated, or disclosed, in whole or in part, without the prior written consent of
International Securities. The recipient further agrees to regard all information
contained herein as the exclusive intellectual property of International Securities,
with this obligation continuing in perpetuity.
The information contained in this document has not been
independently verified by International Securities, its affiliates, directors, officers,
employees, agents, or advisors. This document is based on information obtained from
publicly available sources and other sources that International Securities believes to
be reliable; however, the accuracy or completeness of such information has not been
independently verified. Consequently, International Securities does not make any
representation or warranty, express or implied, regarding the accuracy, correctness,
completeness, or reliability of the information contained herein. Any reliance on this
document or its contents is at the recipient's sole risk, and International Securities
expressly disclaims any and all liability including direct, indirect, or consequential
losses or damages arising from the use of or reliance on this document.
This document does not constitute an offer, invitation,
recommendation, or solicitation by International Securities to purchase or sell any
securities or to engage in any financial transaction or investment activity. It should
not be regarded as forming the basis of or as a substitute for independent professional
advice. Recipients are strongly advised to perform their own and proper due diligence
and seek advice from legal, tax, financial, or other relevant advisors before making any
investment decision.
The contents of this document may include forward-looking
statements, projections, or estimates prepared by third parties. These are inherently
uncertain and subject to risks, assumptions, and factors beyond International
Securities' control that may cause actual outcomes to differ materially from those
anticipated. International Securities provides no assurance nor any form of guarantee
regarding the achievement or reasonableness of any such statements.
By receiving this document, the recipient understands,
acknowledges and irrevocably agrees to the limitations and conditions set out above.
International Securities reserves the right, at its sole discretion, to amend, update,
or terminate the distribution of this document at any time without a prior notice or
obligation to provide any further information or explanation.
|
|